
Jonathan Portes delves into the data on the economic performance of the UK after its exit from the EU’s single market and customs union on 1 January and assesses the real-world impact of these new trade barriers
The economics profession came in for opprobrium and derision after the 2016 EU Referendum, when the recession predicted by the Treasury and the International Monetary Fund failed to materialise.
While not all economists share the blame for then Chancellor George Osborne’s scaremongering, it is fair to say that at least some of the criticism was justified.
Before the Coronavirus pandemic, the UK’s economic performance was mediocre – worsened in part by the vote to leave the EU, as uncertainty hit the pound, and reduced investment, which stagnated after the referendum. But it was not disastrous, as most businesses simply opted to wait to see what would happen, rather than rushing for the exit.
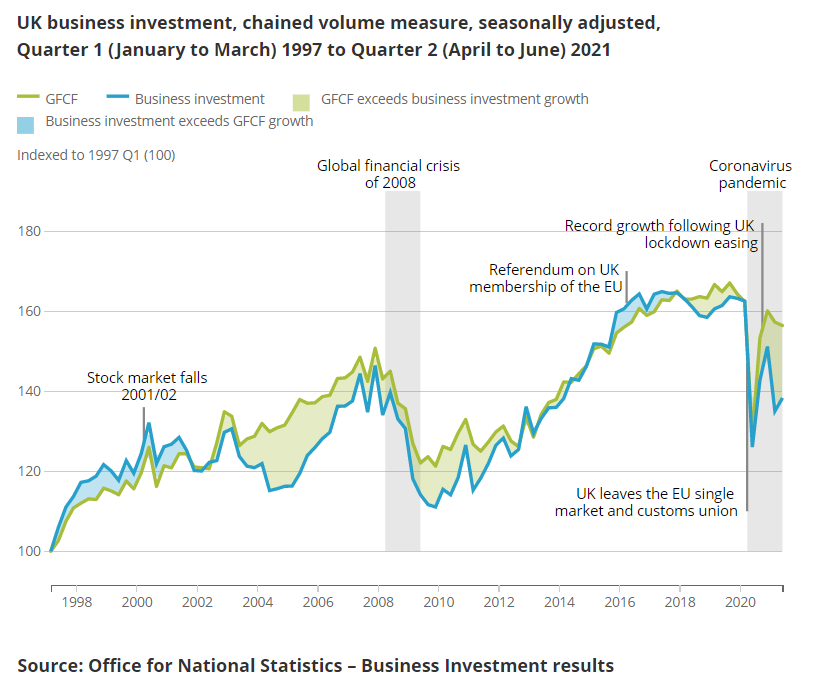
But, somewhat paradoxically, analysing the impact of economic changes is easier over the long than the short-term – it is easier to forecast the climate than the weather.
Forecasting the short-term impact of the Brexit vote was, by definition, about assessing the impact of a political shock on essentially psychological variables – consumer and business confidence, and expectations about future policy. Neither economics nor anyone else has a great track record on this. In retrospect, the fact that predictions were way off should not have been a great surprise.
But, over the longer term, Brexit is primarily about changes to the trading relationship between the UK and the EU. And here, economics and economists, can do better. There are a lot of issues in economics that are controversial, but the principle that increasing trade barriers between two trading partners will reduce trade, and that in general that will reduce economic welfare on both sides, really isn’t.
While putting precise numbers on those impacts is hard, and requires complex economic modelling, it really would be surprising – and a genuine challenge to conventional economics – if Brexit didn’t do some damage to the UK economy. While there was no shortage of politicians who argued that somehow new trade barriers would not make much difference, or that trade with our closest and largest single trading partner could easily be substituted with trade with the rest of the world, no credible economic analysis endorsed such claims.
So, with six months of data on the economic performance of the UK after its exit from the EU single market and customs union on 1 January, what can we say about the real-world impact of these new trade barriers?

Trade
The initial impacts were very much as trade experts – and common sense – would have predicted: trade with the EU, especially imports, rose sharply immediately before the turn of the year, as businesses stockpiled goods in anticipation of Brexit-related disruption; then fell even more sharply, before slowly recovering.
Most of these transitional impacts should have worked through by now. Perhaps surprisingly, UK exports of goods to the EU have now recovered roughly to their pre-Coronavirus levels. But imports from the EU are down substantially, by about 10% compared to two years ago, partly offset by an increase in imports from the rest of the world.
The most surprising – and arguably worrying – statistics relate to the UK’s exports to the rest of the world. Far from Brexit providing a boost, these are also down by about 10%. And this is not an effect of the Coronavirus – EU exports to the rest of the world have increased, not decreased.
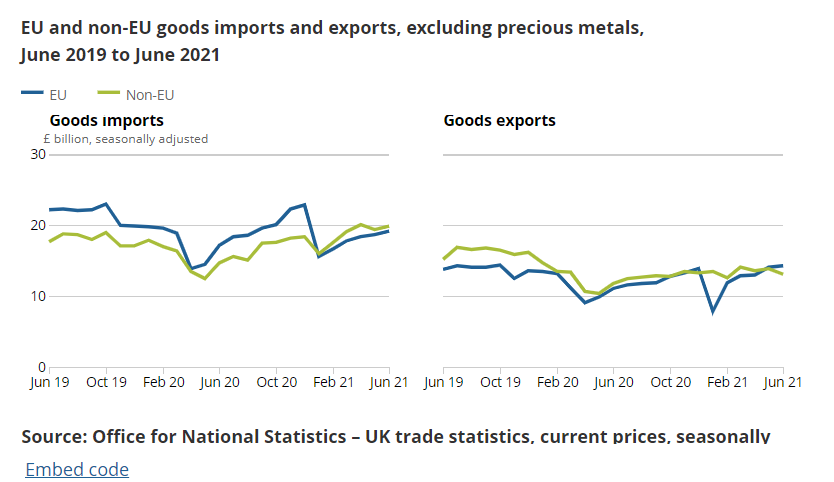
Overall, therefore, the UK’s trade performance has been extremely weak.
How much of this is due to Brexit is unclear. The data is noisy and unreliable and will almost certainly be revised. And we know even less about services trade, which makes up about 40% of UK exports to the EU, although a much smaller share of imports.
There hasn’t been much disruption to financial services, but that doesn’t mean that Brexit doesn’t matter. Firms knew that it was coming, and the picture remains a slow and gradual transfer of some business to continental Europe. In other business services – including law, accountancy, and creative sectors – trade is more dependent on the physical movement of persons, meaning that the impact may be larger but has so far been obscured by Coronavirus-related restrictions.
Perhaps more importantly, it is still very early days. The models described above look at effects over the long-term – say 10 or 15 years – rather than six months. Over time, as companies restructure their supply chains or decide where to invest, the impact is likely to grow. But, so far at least, there is no reason for economists to change their minds about Brexit and trade.
Wages
On wages, the economic consensus was reasonably clear. Just as new trade barriers reduce trade and make us somewhat worse-off, so do barriers to the movement of people. So ending free movement will hit growth. But migration, like trade, also has distributional impacts – workers who compete with migrants might in theory benefit from reductions in immigration.
However, the evidence also suggested that any such impacts would be small. A study by Bank of England economists (often cited by anti-immigration activists) found that wages in the most affected sectors might have been pushed down by about 1% over a decade of high immigration – an impact the study’s authors described as “infinitesimal”, compared to the other drivers of pay.
More importantly, simply looking at the direct impact misses the point. If lower immigration reduces overall growth and productivity, and hence tax revenues, then the average worker will certainly lose out, and even those workers who gain directly can end up losing indirectly. My own pre-Brexit analysis suggested that these indirect effects would indeed dominate.
So do reports of staff shortages and – so far largely anecdotal – higher wages in those sector